Efficient Market Hypothesis for Traders | Quberas
Ask ten traders whether markets are efficient and you'll get ten different answers, but the theory itself makes one specific claim: at any given moment, an asset's price already reflects all available information about it. If that's true, no amount of chart reading or news analysis should let you consistently beat the market — because the market has already "read" the same information and priced it in. The efficient market hypothesis (EMH) doesn't say prices are always right in some cosmic sense; it says prices adjust so fast to new information that finding an edge through analysis alone is, in theory, close to impossible.
What Is the Efficient Market Hypothesis?
The efficient market hypothesis holds that asset prices — stocks, currencies, crypto, whatever you're trading — incorporate all available information almost instantly. A company's earnings beat, a central bank rate decision, a viral rumor on social media: the theory predicts that by the time you've read about it, the price has already moved to reflect it. There's no lag for a sharp analyst to exploit, because thousands of other participants are processing the same information at the same time.
This idea is closely tied to random walk theory, which argues that price changes are essentially unpredictable and independent of past movements — meaning tomorrow's price change tells you nothing useful from today's pattern. If markets are efficient, price charts should look less like a readable story and more like statistical noise. This is exactly the friction point for anyone trying to systematize a strategy: if you're building rule-based logic and want to see precisely where those rules would have fired historically, tools like Quberas exist to make that testing visual and fast rather than theoretical, so you can check the claim against real data instead of taking it on faith. Before going further, it's worth understanding where this theory came from and what, exactly, it's claiming — because the strict version and the practical version are not the same thing.
History and Origin of EMH (Eugene Fama)
The efficient market hypothesis was formalized by Eugene Fama, an economist at the University of Chicago, through a series of papers culminating in his influential 1970 review "Efficient Capital Markets: A Review of Theory and Empirical Work." The groundwork was laid in the 1960s, a period when finance was shifting from descriptive, anecdotal analysis toward statistical and mathematical modeling. Fama built on earlier random walk research from the 1950s and 60s and gave it a rigorous framework, arguing that competition among informed investors drives prices toward their "true" value almost as soon as new information appears.
The work eventually earned Fama a share of the 2013 Nobel Memorial Prize in Economic Sciences, and EMH became a foundational pillar of academic finance theory — taught alongside portfolio theory and asset pricing models as one of the core ideas shaping how economists think about markets. It's important to note that Fama didn't claim markets are perfectly efficient at every instant; he proposed a spectrum of efficiency, which is where the three forms come in.
The Three Forms of EMH: Weak, Semi-Strong, and Strong
Fama split the hypothesis into three versions, each making a progressively bigger claim about what information is already baked into price.
Weak Form Efficiency
Weak form efficiency claims that current prices already reflect all historical price and volume data. If this form holds, technical analysis — the practice of studying past price charts, patterns, and indicators to predict future moves — shouldn't produce a durable edge, because everything in the historical record is already priced in. Under weak form efficiency, a moving average crossover or a chart pattern carries no genuine predictive power beyond chance.
Semi-Strong Form Efficiency
Semi-strong form efficiency goes further, claiming prices reflect all publicly available information — not just past prices, but earnings reports, economic data, news, and filings. If true, fundamental analysis (evaluating a company's financials, industry position, or macro conditions to estimate intrinsic value) also loses its edge, since the moment public information is released, the price has already adjusted before most traders can act on it.
Strong Form Efficiency
Strong form efficiency is the most extreme version: it claims prices reflect all information, public and private, including insider information. Under this version, even someone with non-public knowledge of a company's internal decisions couldn't reliably profit, because the price would already account for it. This form is widely considered unrealistic — insider trading laws exist precisely because insider knowledge does move markets, which is itself evidence against strong form efficiency holding in practice.
Assumptions Behind the Efficient Market Hypothesis
EMH isn't a law of nature; it's a model that only holds if certain conditions are met. Understanding these assumptions explains why the theory frequently breaks down in the real world.
- Rational investors — EMH assumes market participants process information logically and make decisions that maximize expected value, without emotional or cognitive distortion.
- Free information flow — the theory assumes information reaches all market participants at roughly the same time and cost, with no meaningful information asymmetry.
- No arbitrage opportunities — it assumes that any brief mispricing gets corrected almost instantly by traders competing to exploit it, closing the gap before it can be meaningfully captured.
- Frictionless trading — implicitly, EMH assumes trades can be executed without significant costs, delays, or liquidity constraints that would prevent prices from adjusting cleanly.
Each of these is a simplification. Real investors panic, chase trends, and anchor on irrelevant reference points. Information doesn't reach everyone simultaneously — institutional desks and newsletter services often have faster access than retail traders. And execution isn't free: spreads, slippage, and fees all create friction that keeps small mispricings from being fully arbitraged away. These gaps between assumption and reality are exactly where critics of EMH focus their arguments.
Criticisms and Real-World Challenges to EMH
The strongest case against strict market efficiency comes from observed market anomalies — patterns that shouldn't exist if prices fully reflected all information, yet show up repeatedly across decades and datasets. The momentum effect, where assets that have recently outperformed tend to keep outperforming over the following months, is one of the most studied anomalies in finance and directly contradicts the idea that past price data carries no predictive information. The value premium — the historical tendency for stocks trading cheap relative to fundamentals to outperform growth stocks over long stretches — was documented as far back as the 1990s, but its record since then is mixed: the effect has weakened and gone through long periods of underperformance in several major markets after becoming widely known. That decay is itself debated evidence, cited by some as a case of markets arbitraging away a known edge, and by others as proof the original pattern was partly a statistical artifact rather than a durable anomaly.
Then there's the Warren Buffett critique, made most famously in his 1984 essay "The Superinvestors of Graham-and-Doddsville": if markets were truly efficient, the consistent long-term outperformance of a cluster of value investors trained under the same philosophy (Buffett included) shouldn't be statistically possible — it should be no more likely than a large group of coin-flippers all landing heads repeatedly. Buffett's argument isn't a rejection of markets being generally hard to beat; it's a challenge to the idea that no one, ever, can develop a repeatable edge.
Bubbles and crashes are the most visible counter-evidence. The dot-com bubble, the 2008 housing collapse, and periodic crypto blow-offs all involve prices detaching dramatically from any reasonable estimate of underlying value, followed by violent corrections — a pattern that's hard to reconcile with a market that's supposedly pricing in all available information rationally at every step.
EMH vs Behavioral Finance
Where EMH assumes rational actors, behavioral finance studies how real investor psychology actually shapes prices — and it has become the leading counter-framework to strict market efficiency. Behavioral finance researchers, including Nobel laureates Daniel Kahneman and Richard Thaler, catalog specific cognitive biases that distort decision-making: overconfidence, loss aversion (feeling losses more intensely than equivalent gains), recency bias (overweighting recent events), and confirmation bias, among others.
One of the most market-relevant behavioral patterns is herd behavior — the tendency of investors to follow the crowd rather than independently evaluate information, amplifying moves in both directions and creating the kind of overshoot that produces bubbles and crashes. Herd behavior explains why prices can trend for extended periods beyond what fundamentals justify, and why panic selling can push assets well below reasonable value estimates during a crash.
The key distinction is one of mechanism, not just outcome: EMH says prices are hard to beat because they're already correct; behavioral finance says prices can be systematically wrong for stretches of time because human psychology introduces predictable distortions — and predictable distortions are, in principle, more exploitable than random noise.
Does EMH Mean Trading Strategies Are Useless?
This is the question that actually matters for anyone building a system. The honest answer is nuanced: EMH is generally strongest at longer horizons and larger, more liquid markets, and weaker at shorter horizons, smaller markets, and less-followed assets — which is exactly where short-term inefficiencies tend to surface.
This is part of why the passive vs active investing debate exists. For long-term, broad-market exposure, decades of data support the idea that low-cost passive index investing beats the majority of actively managed funds after fees — a point consistent with semi-strong efficiency at that scale. But that doesn't settle whether narrower, rule-based, short-term approaches can find an edge in specific conditions: a particular volatility regime, a specific pair's tendency to mean-revert, or a recurring pattern around certain market hours.
This is where algorithmic trading and systematic strategies live — not as a rejection of EMH, but as a way of testing, case by case, whether a specific market or timeframe shows the kind of persistent, exploitable pattern the theory says shouldn't exist. The point isn't to argue EMH is wrong in general. It's to stop assuming it's uniformly true everywhere, for every asset, at every timeframe, and instead check.
Practical Implications: Testing Ideas Instead of Assuming Efficiency
The problem with debating EMH abstractly is that it's a debate you can't win from an armchair. The more useful move is to treat a strategy idea as a testable claim: does this specific rule, on this specific asset and timeframe, show a real, repeatable pattern — or does it dissolve once you look at enough historical data?
Backtesting — running your rules against historical price data to see how they would have performed — is the direct way to answer that. It's also worth remembering that backtesting is only one required stage; a strategy that looks good historically still needs to be checked with forward testing on live or simulated data before real capital goes behind it, since neither stage alone is considered sufficient proof a strategy is ready. This is where rule transparency matters: it's not enough to see a backtest's final return number, you need to see exactly which conditions triggered which trades, and when, to judge whether the result reflects a genuine edge or a handful of lucky trades.
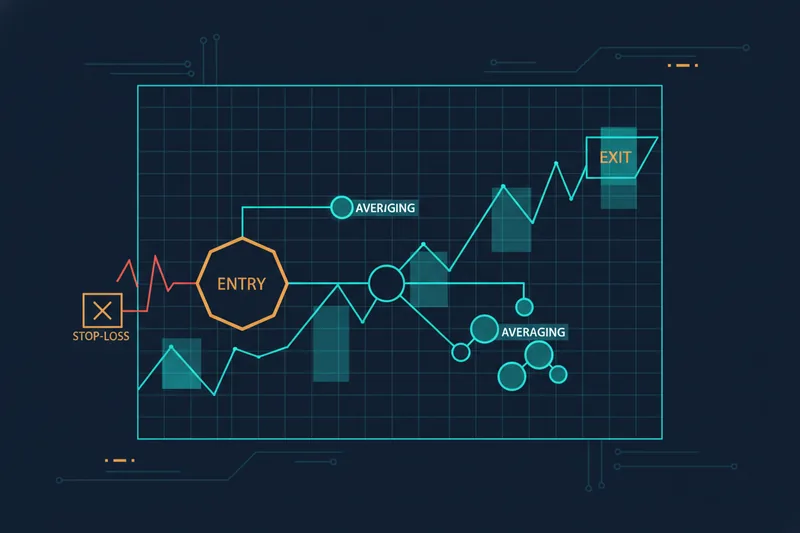
This is the gap Quberas is built to close. Its no-code strategy builder lets you define entry, averaging, exit, and stop-loss logic visually, as a connected map of conditions, without writing code. Its visual debugger highlights the exact chart zones tied to each condition as you test, so you can see not just whether a rule triggered, but how close a near-miss came, and adjust thresholds based on what actually happened on the chart rather than a black-box output. That combination turns "is the market efficient" from a philosophical debate into a specific, checkable question about your own rules, your own asset, and your own timeframe.
If you've got a strategy idea you can't stop thinking about, don't settle the efficient-market question by opinion. See whether it actually holds up — build it visually and backtest it for free with Quberas before you decide the market is (or isn't) efficient.